The line between financial and non-financial companies is dissolving faster than most traditional banking executives anticipated. In 2026, the most significant competition to established banks doesn’t come from other banks — it comes from e-commerce platforms, ride-sharing apps, HR software companies, and social media platforms that have quietly built financial service capabilities into their core products. This is embedded finance: the integration of financial services — payments, lending, insurance, banking — into non-financial platforms and products. Understanding embedded finance is essential for anyone investing in, working in, or disrupted by financial services.
What Embedded Finance Actually Means
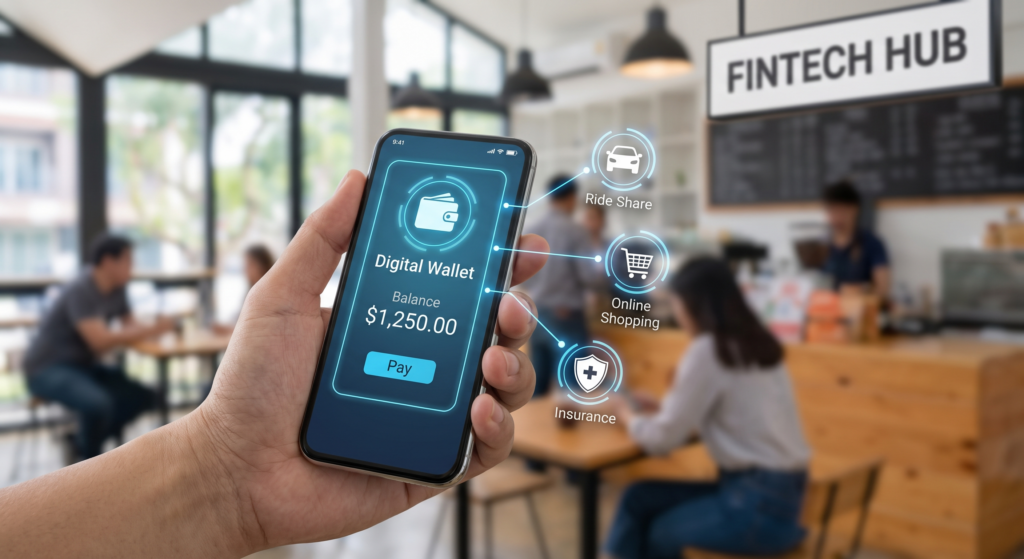
Embedded finance is not a new product category — it’s a distribution model. Instead of customers going to a bank or financial institution for financial services, those services come to them embedded within the non-financial contexts they already inhabit. When Shopify offers merchant loans (Shopify Capital), when Uber provides driver banking accounts (Uber Money), or when Apple offers a savings account (Apple Savings via Goldman Sachs), these are embedded finance products — financial services integrated into non-financial platforms.
The Infrastructure Layer: Banking-as-a-Service
Embedded finance is enabled by Banking-as-a-Service (BaaS) providers — companies that license their banking infrastructure (regulated bank charters, payment rails, compliance frameworks) to non-financial businesses via API. Companies like Unit, Synapse (before its collapse in 2024), Treasury Prime, and Column Bank allow tech companies to offer financial products without obtaining their own banking licenses or building regulatory infrastructure from scratch. The BaaS model transforms banking infrastructure into a commodity API service — profoundly changing the economics of financial product distribution.
Embedded Finance Market Size
| Segment | 2023 Market Size | 2030 Projection | CAGR |
|---|---|---|---|
| Embedded payments | $54B | $178B | 18.5% |
| Embedded lending (BNPL + B2B) | $21B | $129B | 29.2% |
| Embedded insurance | $63B | $170B | 15.2% |
| Embedded banking/accounts | $19B | $66B | 19.4% |
| Total | $157B | $543B | 19.4% |
Embedded Finance in Action: Key Sectors
Embedded finance is manifesting differently across sectors, with distinct product types, business models, and competitive dynamics.
E-commerce and Retail: BNPL and Merchant Lending
Buy Now, Pay Later (BNPL) is the most visible consumer embedded finance product. Klarna, Affirm, Afterpay, and PayPal’s Pay Later are embedded at the checkout of thousands of retailers, offering consumers installment credit without requiring a traditional credit application process. For merchants, BNPL increases average order values (typically 30–50%) and conversion rates, making it a compelling embedded product despite the interchange and risk costs. Merchant lending — working capital loans to small businesses based on sales data rather than traditional credit underwriting — is the B2B equivalent, with Shopify Capital, Square Capital (now Block), and PayPal Working Capital leading the market.
Software Platforms: Vertical SaaS Finance
Vertical SaaS companies — software serving specific industries like restaurants, salons, property management, or healthcare — are embedding financial services as an additional revenue layer. Toast (restaurant management) offers Toast Capital for restaurant loans. Mindbody (fitness and wellness) offers payment processing and financing for studios. Procore (construction) has integrated financial services for contractors. The data advantage is significant: these platforms have granular visibility into their customers’ operational performance, enabling underwriting that traditional lenders cannot match.
Gig Economy and Employment Platforms
Platforms that manage the financial relationships between gig workers and companies have strong embedded finance opportunity. Earned Wage Access (EWA) — allowing employees to access earned but unpaid wages before payday — is embedded in HCM platforms like ADP, Gusto, and Rippling through partnerships with providers like DailyPay and Even. For gig platforms, neo-banking products tailored to income variability (like Lyft Direct or DoorDash’s banking product) address the unique financial needs of gig workers while deepening platform stickiness.
The Business Model Economics of Embedded Finance
Understanding why non-financial companies are pursuing embedded finance requires understanding the economics that make it attractive.
Revenue and LTV Impact
Financial services generate recurring, high-margin revenue streams that dramatically increase customer lifetime value for the embedding platform. Shopify’s financial services revenue (merchant loans, payment processing, banking accounts) now represents over 60% of total revenues — having started as a pure SaaS company. The company effectively transforms a one-time subscription relationship into a multi-product financial relationship with each merchant, with each additional financial product adding incremental lifetime value without proportional acquisition cost.
The Data Flywheel
Platforms with embedded financial services generate transaction data that improves underwriting accuracy, enabling lending to customers that traditional banks would decline or price unfavorably. Better data → better underwriting → lower default rates → ability to offer better pricing → competitive advantage in customer acquisition. This self-reinforcing data flywheel is why established embedded finance players are difficult for traditional financial institutions to displace once established.
Risks and Regulatory Landscape
Embedded finance’s rapid growth has attracted regulatory attention, and the compliance landscape is evolving in ways that investors and participants must track carefully.
BaaS Regulatory Risk
The collapse of Synapse in 2024 — a major BaaS middleware provider — created significant disruption for the fintech companies built on its infrastructure and exposed the risks of the BaaS model’s complexity. US bank regulators (OCC, FDIC, Federal Reserve) have significantly increased scrutiny of bank-fintech partnerships, issuing guidance requiring banks to maintain robust oversight of their fintech partners. This regulatory tightening increases compliance costs and reduces the number of banks willing to serve as BaaS partners, potentially slowing embedded finance growth in regulated markets.
BNPL Regulation
BNPL is under increasing regulatory scrutiny globally. The UK FCA brought BNPL under consumer credit regulation in 2025. The EU’s revised Consumer Credit Directive extended coverage to many BNPL products. The CFPB has issued guidance treating BNPL as equivalent to credit cards for many regulatory purposes. Regulatory compliance costs are rising for BNPL providers and are likely to increase price competition and consolidation in the sector.
Frequently Asked Questions
What’s the difference between embedded finance and open banking?
Open banking refers to regulated frameworks (like PSD2 in Europe and the CFPB’s Open Banking Rule in the US) that require banks to share customer data with third parties via APIs, with customer consent. Embedded finance refers to the integration of financial services into non-financial platforms. Open banking is an enabler of embedded finance but is not identical to it — embedded finance products can be built without open banking data, and open banking data enables financial products beyond embedded contexts.
Is embedded finance a threat to traditional banks?
It is a structural challenge, but not an existential threat in the near term. Banks provide the regulated infrastructure that embedded finance depends on — the bank charter, FDIC insurance, and access to payment rails that BaaS providers license. The threat is to distribution: banks may find themselves relegated to infrastructure providers while non-financial companies capture the customer relationships and fee economics. The most forward-looking banks are building their own embedded finance capabilities and API infrastructure to compete as both infrastructure and product providers.
What are the best investment opportunities in embedded finance?
Compelling investment themes in embedded finance include vertical SaaS companies with demonstrated financial services revenue growth, BaaS infrastructure providers with strong bank partnerships and regulatory compliance track records, and companies in large transaction-volume verticals (real estate, healthcare, construction) where financial services integration is still early. Avoid BNPL pure-plays with undifferentiated products facing margin compression from regulation and competition.
Conclusion
Embedded finance represents one of the most significant structural shifts in financial services distribution since the advent of online banking. The companies that understand this shift — both as an opportunity and a competitive threat — will be far better positioned than those treating it as a fintech trend rather than a fundamental re-architecting of where financial services are delivered and who captures the value from delivering them. For investors, the embedded finance opportunity is not in the undifferentiated infrastructure layer but in the vertical specialists with genuine data advantages and the scale to sustain the regulatory compliance costs that embedded financial services require.